September Luxury Inventory Rebuilds as Contracts and Sales Rise
Here’s my quick read on what changed this month in the Scottsdale, Paradise Valley, and Phoenix luxury markets—and what it means for homeowners and buyers.
September Market Pulse
Greater Scottsdale’s luxury market entered fall with substantially more inventory, accompanied by increases in contracts and completed sales.
Active inventory increased to 1,545 properties priced at $1 million or more—15.5% above August but still 5.9% below September 2025.
Under-contract inventory reached 487 properties, increasing 6.1% from August and 15.4% year over year. Closed sales also improved, rising 16.7% from August to 294, although that total remained 3.3% below last September.
New listing activity recorded the largest monthly change. September brought 690 new listings—47.1% more than August and 4.6% more than one year ago.
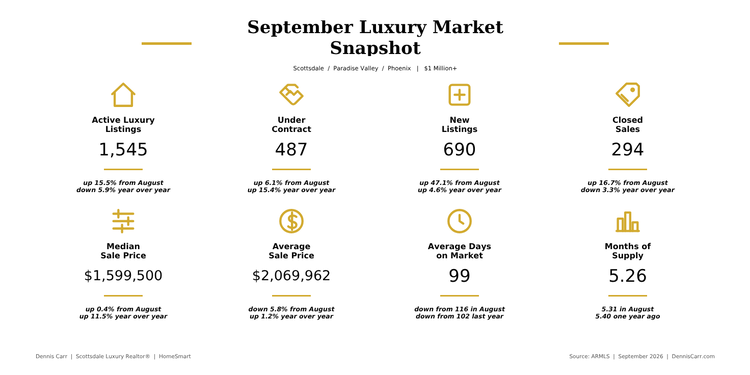
Despite the increase in available homes, months of supply remained essentially unchanged at 5.26, compared with 5.31 in August and 5.40 last year.
That combination is important. The fall inventory rebound gave buyers more choices, but improving contract and closing activity kept overall supply from increasing materially relative to demand.
September Pricing
The median luxury sale price reached $1,599,500, increasing 0.4% from August and 11.5% from September 2025. The average sale price was approximately $2.07 million, down 5.8% from August but 1.2% above last year.
Median sold price per square foot was approximately $529—essentially unchanged from August and 6.1% higher year over year. Average sold price per square foot was approximately $567, down 2.5% monthly but 3.5% higher annually.
The difference between median and average results reinforces the importance of property mix. Monthly luxury figures can change considerably depending on the size, location, price range, and characteristics of the properties that close.
September’s pricing results should therefore be treated as market context rather than an assumption that every luxury property increased or decreased by the same percentage.
Marketing Time Improved
Average days on market declined from 116 in August to 99 in September. That was also slightly faster than the 102-day average recorded last September.
Median days on market declined from 79 to 76. That remained close to last year’s median of 74 days.
The improvement suggests that September’s stronger activity was not driven only by additional inventory. Properties also moved through the market somewhat more efficiently, although location, condition, price, and presentation continued to produce very different individual results.
Current Mortgage-Rate Context
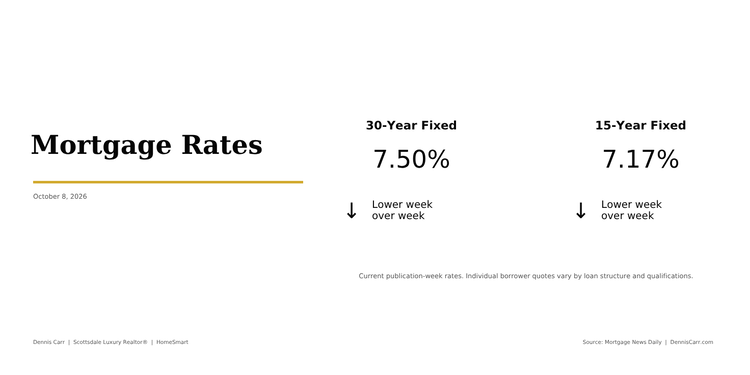
Mortgage News Daily reported the 30-year fixed rate at 7.50% and the 15-year fixed rate at 7.17% on October 8.
These are current publication week readings - not September monthly averages. Financing costs remain high enough to influence purchasing power, property selection, and negotiation strategy, particularly for buyers using larger loan balances.
Conditions Vary by Price Range
September’s overall 5.26 months of supply masks substantial differences across price segments.
Properties priced from $1 million to $2 million carried 4.34 months of supply, while the $2 million to $3 million range had 4.25 months. Those segments remained more competitive than the upper portions of the luxury market.
Supply increased to 6.71 months from $3 million to $4 million and 11.13 months from $4 million to $5 million. The $5 million to $6 million segment carried 13.25 months, the $6 million to $7 million range had 10.33 months, and properties priced at $7 million and above registered 22.5 months.
These figures do not predict how long an individual home will take to sell. They demonstrate why negotiating conditions should be evaluated within the property’s specific price range and competitive set rather than through one market-wide label.
September Luxury Market Watch
September’s highest-priced recorded closing was 24258 N. 91st Street in Scottsdale, which sold for $14 million, or approximately $654 per square foot.
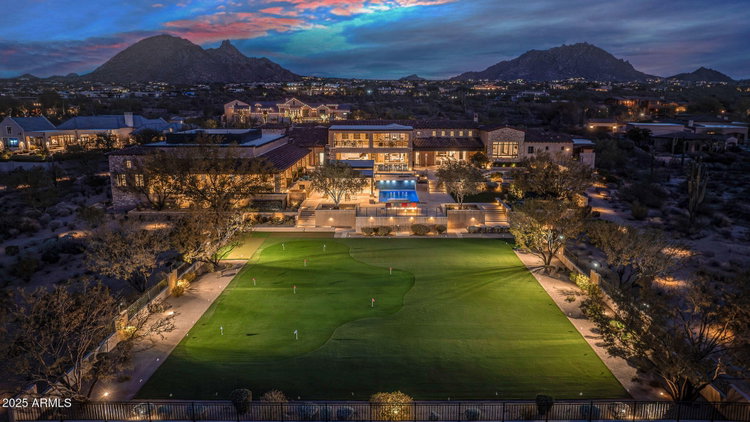
Known as HardtSeasons, the 21,410-square-foot compound is situated on nearly five acres within Prado Estates. The property includes substantial residential and guest accommodations, two resort-style pools, extensive indoor and outdoor entertaining areas, and expansive mountain and city views.
It closed after 20 cumulative days on market, approximately 21.8% below both its final and original list price of $17.9 million.
The transaction demonstrates continued purchasing capacity at the highest end of the Scottsdale market. It also illustrates that even highly distinctive estates remain subject to price discovery when the original positioning exceeds the value buyers are prepared to recognize.
What the September Market Means
September produced a constructive fall transition. Buyers received substantially more new choices, while contracts and completed sales increased enough to keep months of supply essentially unchanged.
For Buyers
The inventory rebound should improve selection, particularly as additional fall listings reach the market. However, under-contract inventory standing 15.4% above last year indicates that demand remains active.
Negotiating leverage is more likely in the upper price ranges and among properties that have accumulated market time, require updating, or compare poorly with competing homes. Desirable properties below $3 million may still face more competitive conditions.
For Sellers
Active inventory remains below last year, but September’s 690 new listings materially increased current competition. Sellers should compare their homes with the properties buyers can purchase now—not only with older closed sales.
Accurate pricing, preparation, condition, presentation, and a clear understanding of the immediate competitive set remain essential. The improvement in marketing time is encouraging, but it does not eliminate the consequences of beginning above the market.
Market Perspective
The most meaningful September signal is the simultaneous improvement in supply and demand.
Active inventory increased 15.5%, but under-contract inventory rose 6.1%, closed sales increased 16.7%, and months of supply remained near its August level. That indicates that the fall inventory expansion was met by meaningful buyer activity rather than broad demand deterioration.
The market remains highly segmented. Conditions below $3 million are notably tighter than those at higher price points, while individual properties continue to perform according to their location, condition, presentation, and value relative to competing choices.
Market statistics reflect residential properties across all dwelling types priced at $1 million and above in Scottsdale, Paradise Valley, and Phoenix.
Real estate decisions are deeply personal. If you’re considering buying or selling in Scottsdale, Paradise Valley, or Greater Phoenix, I’d welcome the opportunity to discuss your goals and how today’s market may influence your decisions.